By ManyWays LLC, MHIC #150485
We are contractors, not insurance agents. Your policy is the final word, and every policy reads a little differently. But we work with homeowners on claims all the time, and the same questions come up. Here is what we usually see.
The short answer
Most standard homeowners policies cover water damage that is sudden and accidental. Think of a pipe that bursts, a dishwasher that leaks, or a storm that tears a hole in your roof and lets rain in.
Most standard policies do not cover flooding that comes from outside, or damage from a problem that built up slowly over time.
That line between "sudden" and "slow" decides many claims.
What is often covered
- A burst or frozen pipe.
- A water heater that fails.
- A washing machine or dishwasher hose that breaks.
- An overflowing tub, sink or toilet.
- Rain that comes in after wind or a tree damages the roof.
In these cases, the policy often pays for drying the home and repairing the damage, minus your deductible.
What is often not covered
- Flood water. Rising rivers, heavy runoff, storm surge and groundwater that comes in from outside are normally excluded. You need a separate flood policy, usually through the National Flood Insurance Program (NFIP) or a private flood insurer. These policies often have a waiting period before they start, commonly around 30 days, so you can't buy one the day a storm shows up.
- Sewer or drain backup. Many policies exclude it unless you added a special endorsement. If your basement has ever backed up, ask your agent about this add-on.
- Slow leaks and neglect. A drip under the sink that went on for months, or a leak that was ignored, is often treated as a maintenance issue.
- Wear and tear. The insurer may pay for the damage the water caused but not for the old pipe that failed.
If you're unsure which bucket your loss falls into, read the water damage section of your policy, or call your agent and ask.
How the type of water matters
Restoration pros sort water into three categories. Clean water from a broken supply line. Gray water from appliances. Black water from sewage or flood. Insurers often treat the third category differently, and it may need a rider. Our water damage restoration page has a simple table that shows how these categories usually line up with coverage.
What to do to protect your claim
- Stop the damage. Shut off the water. Policies expect you to take reasonable steps to prevent more loss. Our first 24 hours checklist explains how.
- Take photos and video. Do it before you move or throw anything out.
- Call your insurance company soon. Most policies require prompt notice. Don't sit on it.
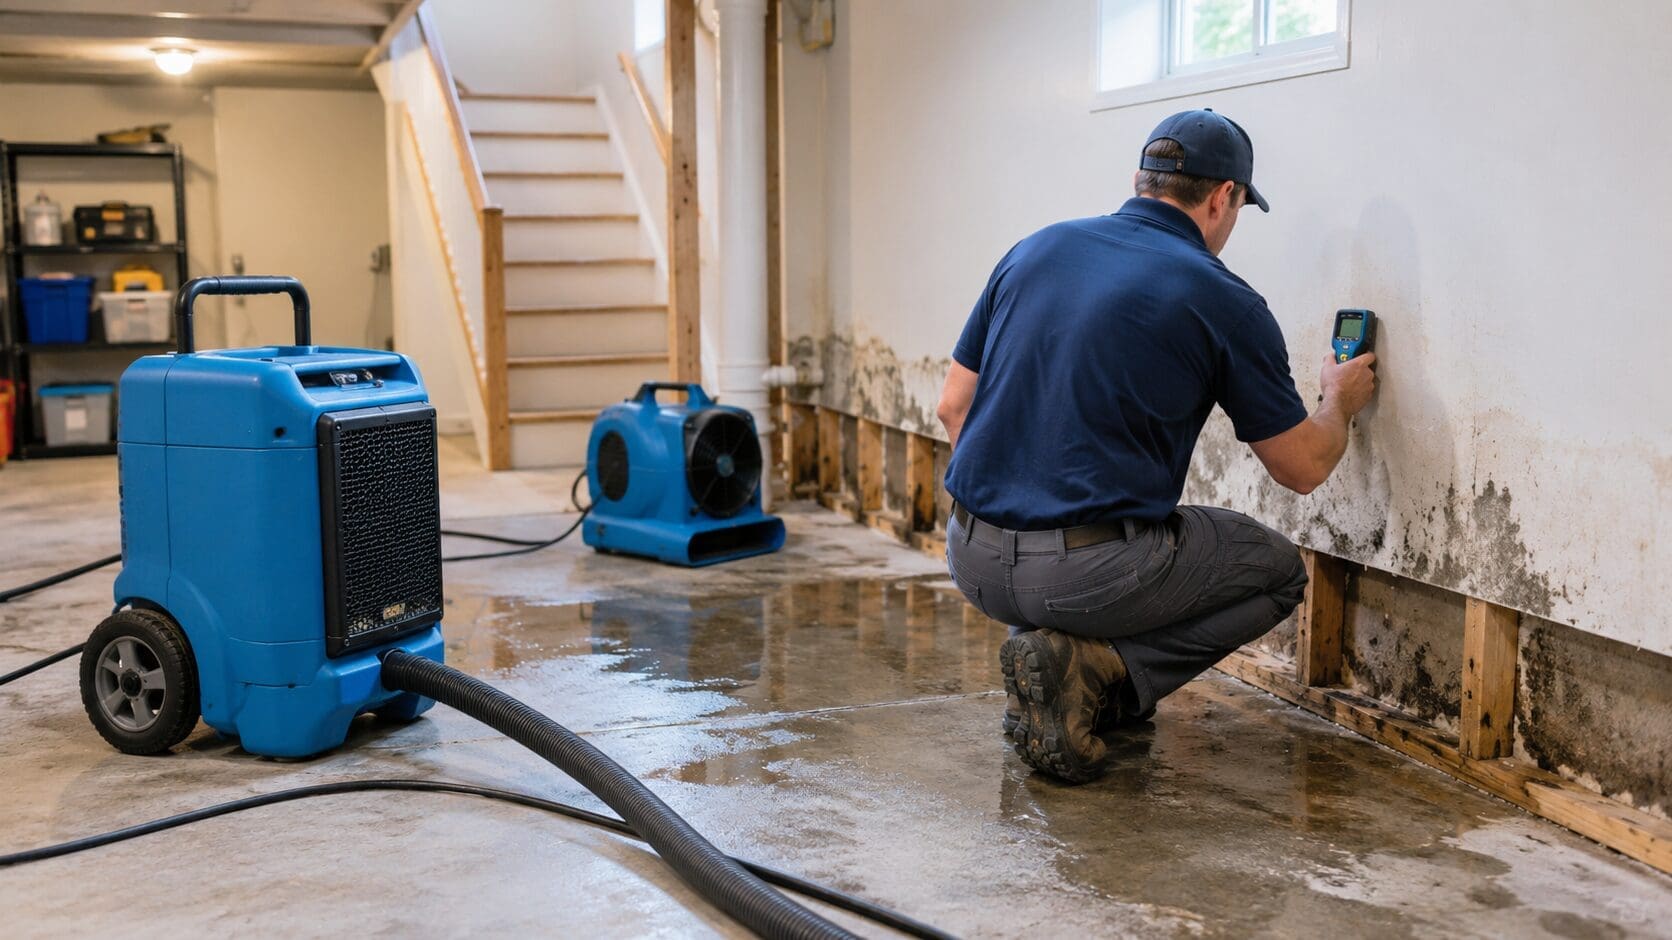
- Start drying quickly. Delay can turn a covered water loss into a mold problem, and mold coverage is often limited. We cover this in how fast mold grows after water damage.
- Keep every receipt. Hotel, storage, equipment, supplies.
- Keep damaged items until the adjuster has seen them, or take clear photos first.
- Get an itemized scope of work. It gives the adjuster a clear list of what needs to be done and what it costs.
What we do for your claim
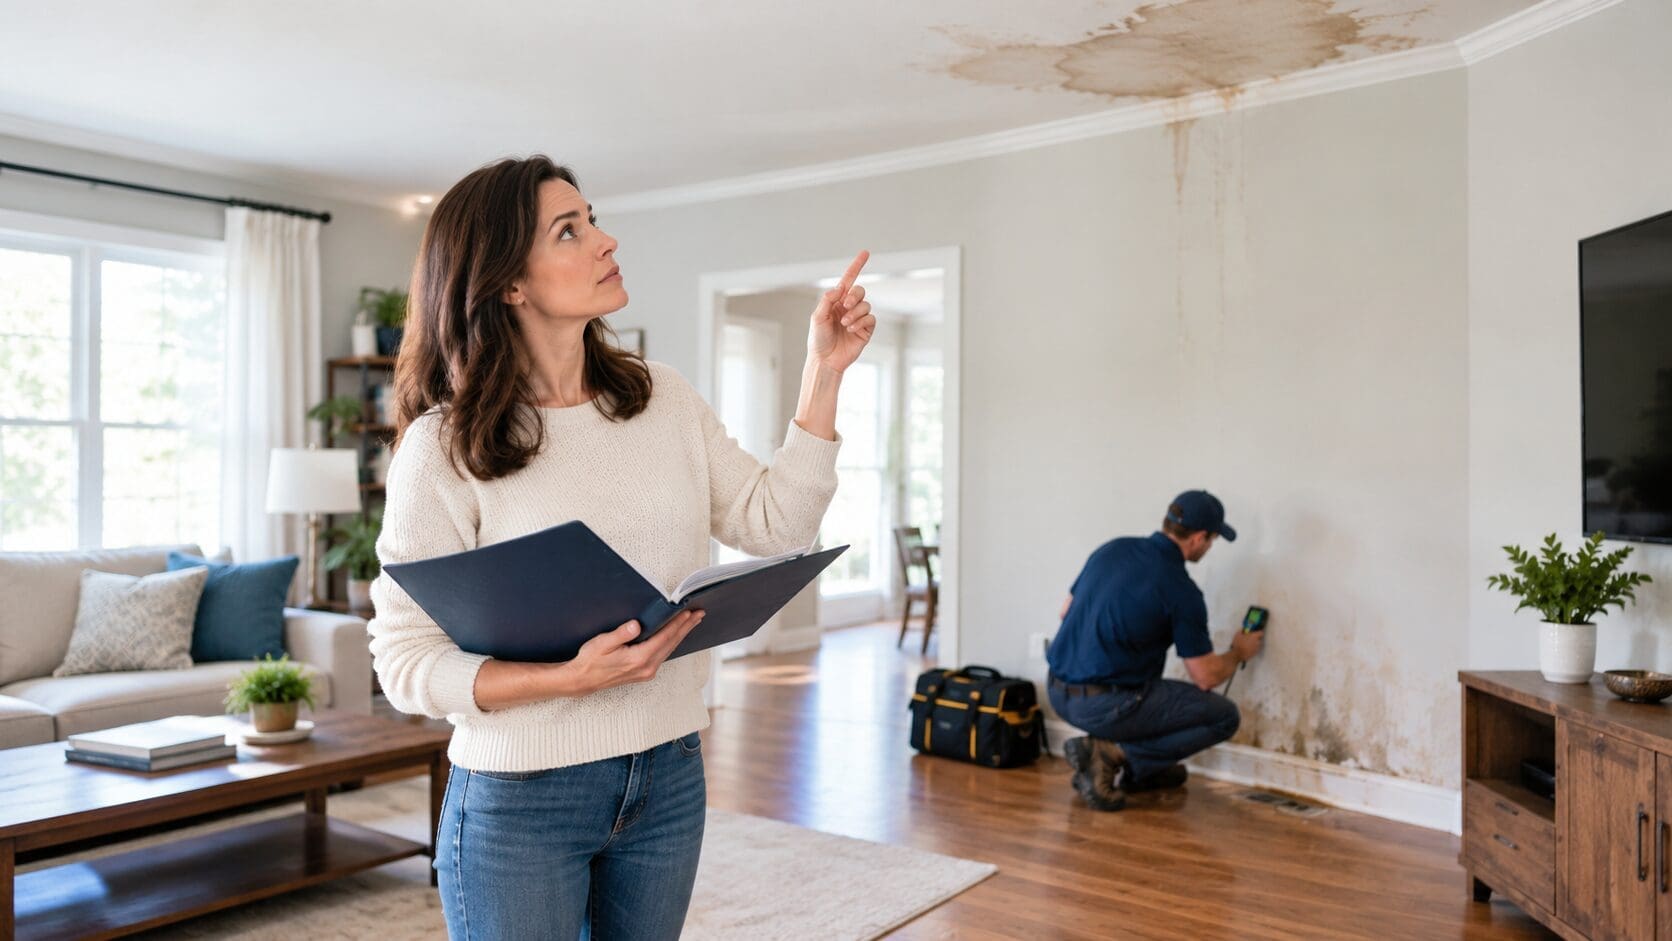
We document the damage with photos and written notes. We write an itemized scope of work in a format adjusters can read. We keep daily drying logs. And we talk to your adjuster when you want us to.
We don't decide whether your claim is approved. Only your insurer does. What we can do is make sure the paperwork shows what really happened.
Should you file a claim at all?
This depends on the size of the loss and your deductible. Small repairs that cost less than your deductible may not be worth a claim. A claim can also affect your premium or renewal, so ask your agent how yours might. For bigger losses, a claim is usually what the policy is for.
If you're not sure of the cost, our guide on water damage restoration costs in Maryland can help you plan.
FAQs
Does homeowners insurance cover a flooded basement?
It depends on how the water got in. A burst pipe is often covered. Groundwater or a drain backup often isn't, unless you have flood coverage or a backup endorsement.
Do I need a separate flood policy?
If your home could take on water from outside, ask your agent about NFIP or private flood insurance.
Can I start cleanup before the adjuster arrives?
Yes, and you should. Document everything first, and keep records of what you do.
Had a loss and need the paperwork done right?
Call (301) 605-2296 or contact us here. We serve Gaithersburg, Potomac, Rockville, Bethesda and nearby areas.
Turn Your Basement Into a Space You’ll Love
A well-designed basement can add valuable living space to your home. From cozy family rooms to modern home offices or entertainment areas, smart basement remodeling ideas help maximize functionality, comfort, and style while increasing your home’s overall value.